


Overall
As anticipated in our preview, this quarter was not an inflection point. While the company provided a positive narrative regarding the AI Agentic Identity Solution, the announced Q4 guidance and the implied clues for FY27 lack strong financial support
The year-over-year (YoY) guidance for Q4 cRPO (Current Remaining Performance Obligations) is only 9%, down from the 13% reported this quarter (the bogey was 13%-14%). This indicates a slowdown in cRPO growth. Although the Agentic AI Solution has achieved General Availability (GA) and is showing initial commercial traction, its near-term impact on revenue growth appears limited.
Furthermore, the company usually provides a preliminary outlook for the next fiscal year in Q3, but it did not do so this year. Management stressed the crucial importance of the Q4 performance for formulating the next year’s outlook. Despite a generally optimistic tone in the company’s descriptions, calculations based on the methodology provided in the earnings release (ER) imply an FY27 growth rate of 9.5%, which represents a further deceleration from FY26.
Other Metrics
Revenue exceeded the high end of the guidance by approximately 2%, consistent with the beat in the previous quarter. The company attributed this strong performance to large customer adoption and robust Workforce Identity upsells, particularly driven by newer products such as Okta Identity Governance (OIG).
However, the reported figures indicate:
YoY growth was 11.6% (down from 12.7% in Q2), showing a deceleration.
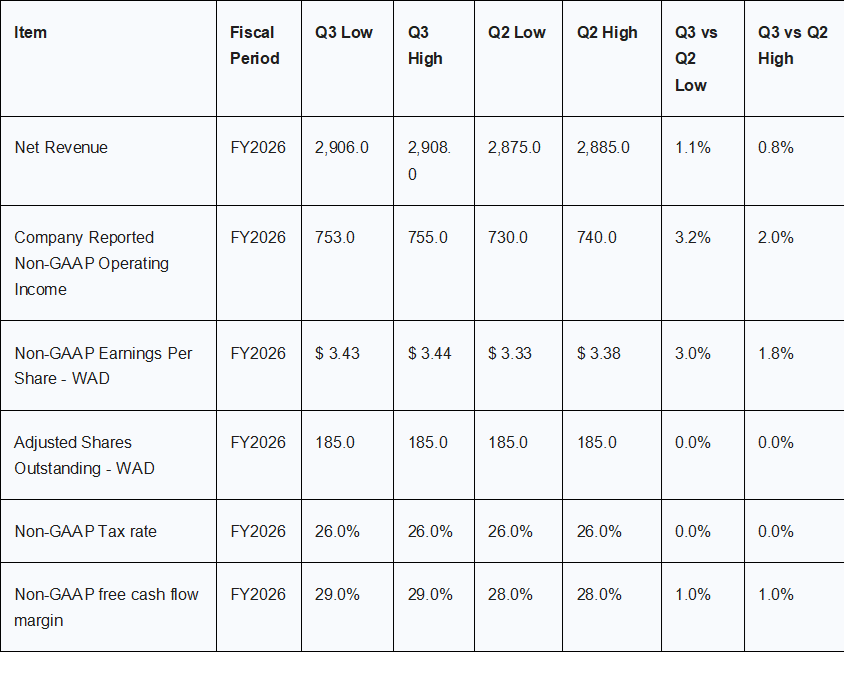
Even with the full-year guidance raise, assuming a Q4 revenue beat of 2%, the projected FY2026 growth rate is 12% (down from 15.3% in FY2025) , also pointing to a slowdown
Key Focus Areas
We believe the earnings discussion should focus on three key areas, despite management’s generally positive, albeit somewhat repetitive, discussions on the importance of Identity in the AI era and the significant TAM expansion:
