

Okta’s Q2 performance came in largely inline with its bogey, showing signs of incremental improvement but not a material business inflection. Based on channel checks, Q3 appears broadly similar: growth is improving at the margin, but the new AI products are contributing very little at this stage. Only a limited subset of partners noted that Agentic Identity has entered POC stages, and revenue contribution remains immaterial. Most partners have not built meaningful acceleration assumptions into their forecasts. Feedback also indicates that pricing, deployment, and go-to-market motions around AI remain unclear—suggesting the company itself is not yet fully ready for scaled commercialization.
The strategic value of identity in the AI Agent era is becoming increasingly evident. Multiple ecosystem developments reinforce this trend, including acquisitions and product launches, including:
Palo Alto Networks acquiring CyberArk (Jul-2025);
ServiceNow announcing its intent to acquire Veza (Nov-2025);
Twilio acquiring Sytch (Nov-2025);
CrowdStrike launching NG Identity Security (Sep-2025);
Cisco introducing a new IAM product (May-2025)
Continuous updates from Microsoft in 2025, including expanded Passkey support, stricter MFA policies for external users, and using Security Copilot to enhance Entra’s IGA capabilities
Although Okta’s core business remains resilient and may even modestly re-accelerate, the competitive landscape has intensified. The company launched capabilities designed to manage AI Agents last quarter, but the solution is viewed as complex, suggesting that customer adoption may take longer.
This quarter’s results are likely to resemble last quarter’s trajectory. Investors will focus on management’s roadmap and commercialization cadence for the new AI portfolio.
Okta Product Lines: Market Feedback and Competitive Dynamics (Based on Channel Checks)
Overall, every major product line faces heightened competition, and AI products have not yet contributed meaningfully to growth.
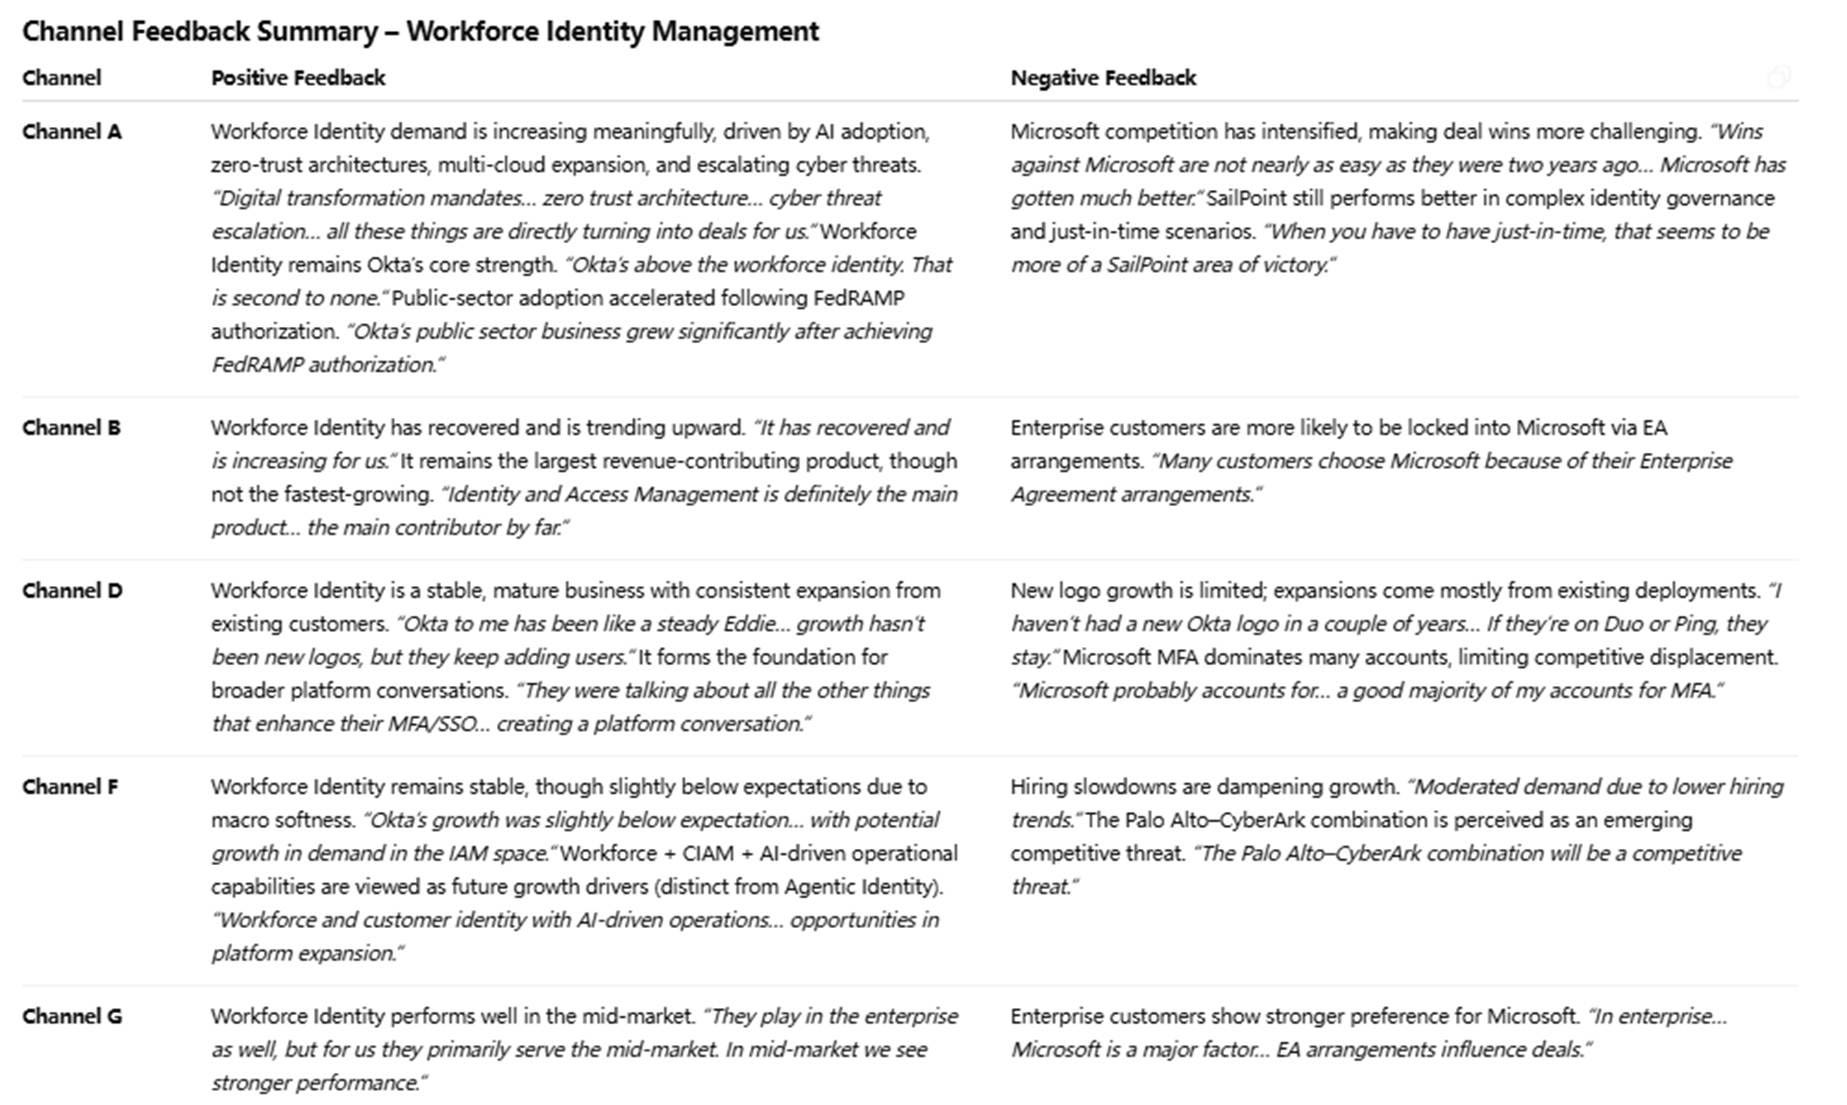
A.1 Workforce Identity Management
Channels uniformly view Workforce Identity as Okta’s core, most resilient, and highest-contributing segment. Demand continues to benefit from zero-trust adoption, multi-cloud architectures, AI-driven security modernization, and rising requirements from public-sector customers.
However, all channels cite intensifying competition from Microsoft, SailPoint, Ping, and CyberArk. A softer macro environment and moderating hiring have further limited incremental identity demand.
A.2 CIAM (Customer Identity / Auth0)
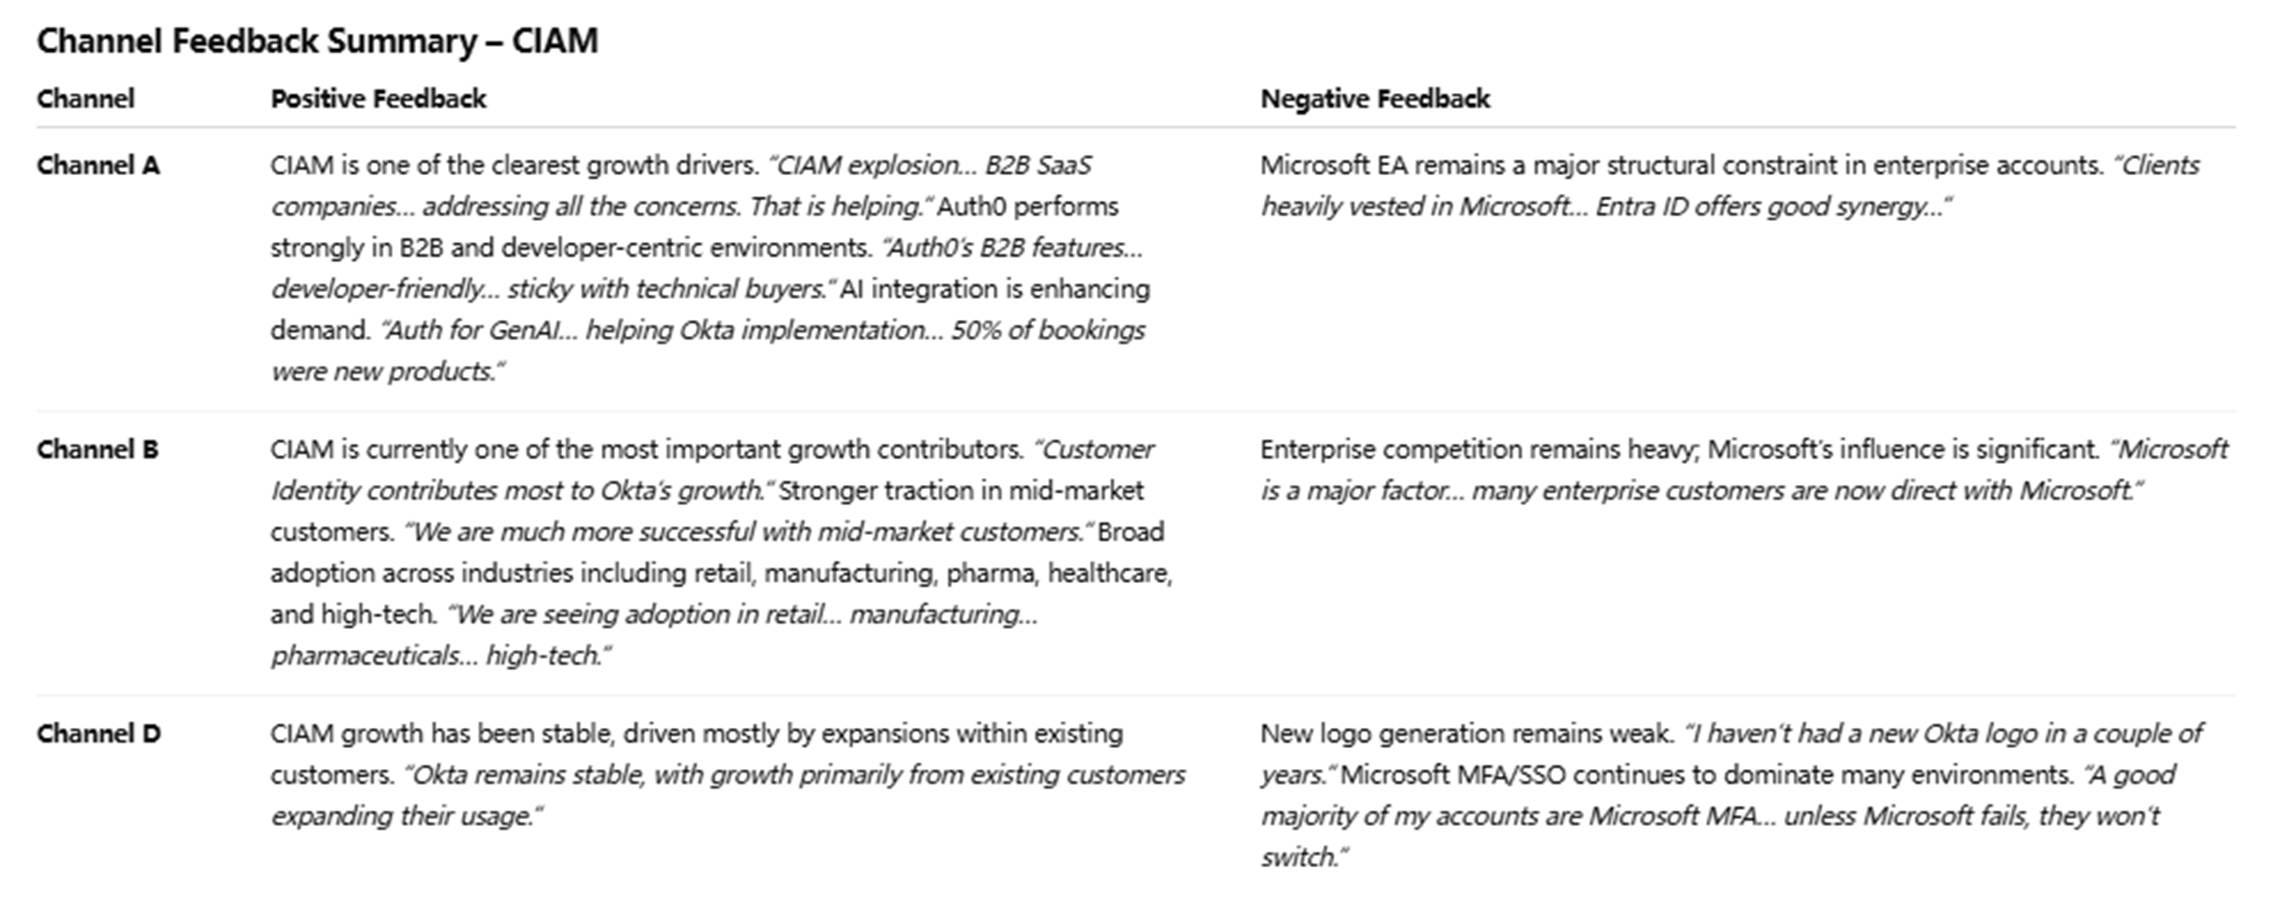
Channels broadly agree that CIAM/Auth0 remains Okta’s strongest growth engine, with meaningful traction across B2B and multiple verticals. Auth0’s developer friendliness and flexibility are key competitive strengths.
Channels generally expect CIAM + Agentic Identity to form the most important growth combination for Okta in the coming years. However, enterprise adoption faces significant pressure from Microsoft Entra, and net-new logos remain limited.
A.3 IGA
Some partners observed incremental growth contribution from IGA, supported by compliance-driven demand and AI-enhanced governance features. However, the market is viewed as relatively mature, with Microsoft EA integration posing the largest challenge.
